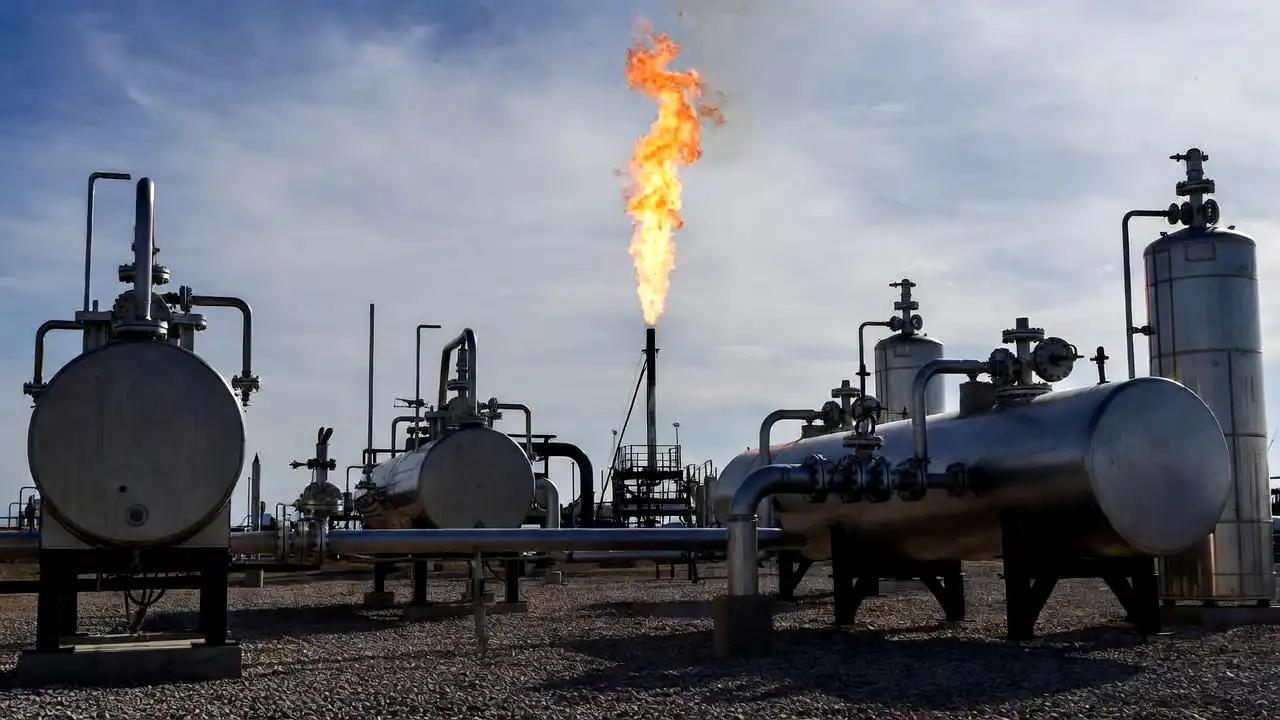
American motorists are pulling up to gas station pumps with mounting frustration as retail fuel prices reach unprecedented levels for this point in an election cycle. The national average price for regular unleaded gasoline has climbed to roughly $4.30 to $4.35 per gallon, while commercial diesel fuel has surged past $6.06 to reach record peaks above $6.23 per gallon. The relentless climb in pump prices defies the historical seasonal pattern where gasoline prices drop in the autumn as summer vacations wind down and refineries switch to cheaper winter fuel blends.
With congressional midterm elections only weeks away, the fuel price surge has transformed energy affordability into the primary kitchen-table issue across the United States. International crude oil benchmarks crossing $100 to $107 per barrel, combined with military conflicts in the Middle East, maritime transit disruptions through the Strait of Hormuz, and damage to critical export pipelines, have created a severe global supply shock.
As high fuel costs feed directly into freight shipping rates, grocery bills, and headline consumer inflation, voters, political candidates, and central bank policymakers face a compounding economic headache that shows little sign of immediate relief.
Anatomy of the Unprecedented Election-Season Fuel Surge
The current spike in retail gasoline prices stands out in modern economic history because of its timing within the annual calendar and the political cycle.
Defying the Autumn Seasonal Price Drop
Under standard market conditions, late summer and early autumn bring predictable downward pressure on retail gasoline prices. As the busy summer driving season concludes after the Labor Day holiday, total domestic gasoline demand typically decreases. Simultaneously, environmental regulators allow fuel terminals to transition from expensive, low-volatility summer-blend gasoline to less costly winter-grade fuel.
This year, that seasonal price drop failed to materialize. Strong underlying consumer demand, tight domestic fuel inventories sitting roughly 7% below historical five-year averages, and surging crude oil input costs have completely overwhelmed standard autumn market patterns.
Instead of seeing prices drift lower toward $3.00 or $3.20 per gallon, drivers have watched daily pump averages climb for weeks. This unexpected counter-seasonal rally has caught household budgets completely unprepared, forcing families to allocate a larger share of their weekly paychecks to basic commuting expenses.
Comparing Pump Prices Across Recent Congressional and Presidential Cycles
Historical price tracking underscores how extraordinary the current price environment is for an election year. In previous election seasons, retail gasoline prices at this exact calendar point hovered at significantly lower baselines:
- Previous Midterm Cycles: During previous midterm elections, the national average for regular gasoline averaged between $3.60 and $3.80 per gallon, while earlier cycles saw nationwide pump averages between $2.85 and $3.35 per gallon.
- Recent Presidential Years: During recent presidential election cycles, late-summer gasoline prices traded within manageable bands, averaging roughly $3.15 to $3.30 per gallon.
- One Year Ago: A year earlier, before regional conflicts broke out and global energy shipping corridors faced closures, the national average for regular gasoline was roughly $3.17 to $3.30 per gallon.
Today’s national average of $4.30-plus per gallon represents a dramatic 30% jump compared to the same period in the prior year. American drivers are paying over $1.00 more for every single gallon of gasoline pumped into their vehicles, creating the most expensive pre-election fuel environment in modern American history.
Geopolitical Energy Shocks and Crude Oil Bottlenecks
Retail gasoline and diesel prices are ultimately tied to the price of raw crude oil, which accounts for more than 50% of the total cost of finished gasoline at the pump. The recent price rally reflects escalating instability across primary global production and transit hubs.
Crude Benchmarks Pushing Past 100 Dollars per Barrel
Global oil markets have experienced rapid upward repricing as international benchmark Brent crude futures advanced past $106 per barrel, and domestic West Texas Intermediate futures surged above $102 to $103 per barrel.
The primary driver behind this crude rally is physical market tightness. Global petroleum demand continues to expand, driven by robust industrial transportation and aviation travel.
However, global spare production capacity remains constrained. Upstream exploration companies, operating under disciplined capital expenditure strategies, have resisted aggressive production over-drilling. When commercial energy demand collides with tight spare capacity, even minor supply interruptions trigger large, asymmetric price spikes on commodity exchanges.
Middle Eastern Transit Friction and Saudi Pipeline Disruptions
The physical flow of crude oil has been severely impacted by military hostilities in the Middle East. Naval friction and drone attacks in waters surrounding the Strait of Hormuz—which historically handles roughly 20% of the world’s daily petroleum supply—have caused commercial tanker transits through the narrow corridor to drop to historic lows.
Compounding this maritime bottleneck, drone strikes damaged a vital pumping station along Saudi Arabia’s 745-mile East-West crude pipeline, taking the 4-million-barrel-per-day overland bypass offline.
With the overland pipeline disabled and maritime shipping through Hormuz heavily restricted, millions of barrels of crude oil are trapped in eastern export terminals. Global refiners that rely on steady Middle Eastern crude deliveries have been forced to outbid one another for alternative physical cargoes from the North Sea, West Africa, and the United States Gulf Coast, driving global crude benchmarks to multi-year highs.
Diesel at Record Highs Sparks Freight and Grocery Inflation
While everyday motorists focus on the price of regular unleaded gasoline, economists and supply chain managers are sounding alarms over the extraordinary price spike in diesel fuel.
Six-Dollar Diesel Squeezes Commercial Trucking Fleets
The national average price for a gallon of commercial diesel fuel has crossed above $6.06, with daily tracking benchmarks hitting all-time highs of $6.23 per gallon. A year ago, diesel traded near $3.70 per gallon, meaning fuel costs for commercial fleet operators have surged by more than 60%.
Commercial diesel represents the essential fuel that powers the American logistics network. Freight locomotives, long-haul semi-trucks, agricultural combines, construction excavators, and river barges run almost exclusively on diesel.
A typical long-haul commercial tractor-trailer holds 150 to 300 gallons of fuel and travels over 100,000 miles every year. At $6.20 per gallon, filling a commercial truck’s dual fuel tanks costs between $930 and $1,860, adding thousands of dollars in weekly operational expenses for independent owner-operators and logistics conglomerates.
Compounding Price Pressures on Packaged Food and Consumer Goods
The diesel price shock does not remain contained within the transportation sector; it spreads rapidly across the entire real economy. Freight carriers routinely add automated fuel surcharges to commercial transport invoices whenever diesel prices rise.
These higher shipping costs are passed directly down the supply chain to wholesale food distributors, regional warehouses, and retail grocery stores. Everything that moves across the country—from fresh produce and meat to paper towels, building lumber, and consumer electronics—becomes more expensive to transport.
Government inflation reports indicate that rising energy and freight costs have accelerated month-on-month Consumer Price Index gains, pushing headline annual inflation back up to 3.4%. The diesel spike threatens to undo months of disinflation, driving up the cost of living for consumers who must already pay elevated prices at retail checkout counters.
Political Battlegrounds and Shifting Midterm Dynamics
The surge in gasoline prices arrived at the most politically sensitive moment of the calendar, shaping candidate messaging and voter sentiment ahead of decisive midterm elections.
Fuel Prices Dominate Kitchen-Table Campaign Debates
Gasoline is unique among consumer goods because its price is displayed on towering, illuminated roadside signs on nearly every commercial street corner in America. Unlike subtle price increases in streaming subscriptions or healthcare services, consumers see the exact price of gasoline every single day as they drive to work, pick up groceries, and run family errands.
In highly competitive congressional districts and battleground Senate races across Pennsylvania, Ohio, Michigan, Nevada, and Arizona, energy affordability has taken center stage.
Challenger candidates are aggressively highlighting $4.30 regular gas and $6.00 diesel, blaming incumbent administration foreign policy decisions and domestic environmental regulations for driving energy costs higher.
In response, governing officials argue that the price spike is the direct result of overseas military conflicts, foreign state pipeline attacks, and corporate pricing behavior by major oil companies. However, political analysts note that voters historically hold the party in power accountable for pump prices, making high fuel costs a massive political liability for incumbents fighting in tight suburban swing districts.
Federal Reserve Monetary Policy Trapped by Energy Inflation
The unexpected resurgence of fuel inflation has placed central bank policymakers in an extremely difficult monetary position. Financial markets had spent months anticipating that central bankers would begin cutting benchmark interest rates to support economic growth.
Instead, sticky headline inflation driven by surging energy prices has forced policymakers to reconsider their monetary easing schedule. Federal Reserve officials have signaled that the central bank cannot cut interest rates while headline inflation accelerates.
Fixed-income markets have begun pricing in the possibility that the central bank may need to hold its benchmark rate near 3.6% or even deliver a quarter-point rate hike to prevent energy inflation from triggering secondary wage-price spirals.
The prospect of higher-for-longer interest rates pushes 30-year residential mortgage rates back above 7% and raises auto loan costs, creating a double squeeze on American households dealing with high gas prices and elevated borrowing costs simultaneously.
State-Level Disparities and Regional Refinery Constraints
While the national average provides a broad snapshot of the fuel market, the pain at the pump varies dramatically across different states due to localized refinery capacity, pipeline connectivity, and state fuel taxes.
West Coast and Mountain States Suffer Steep Regional Premiums
Drivers in Western states are bearing the heaviest financial burden. In California, the state average for regular gasoline has surged to $5.64 per gallon, with retail diesel reaching an astonishing $7.98 per gallon. Washington state at $5.11 for gas and $7.06 for diesel, alongside Hawaii at $5.46 for gas and $7.00 for diesel, has seen prices climb past $5.00 and $7.00 benchmarks.
Western markets suffer from geographic isolation from the massive refining complexes along the United States Gulf Coast. The West Coast relies on localized refineries that operate near full capacity and enforce strict state-mandated environmental fuel blends.
When a single regional refinery experiences an unplanned maintenance outage or crude supply delay, local wholesale gasoline prices spike rapidly. Similar supply pressures have pushed pump prices in Mountain states like Colorado to $4.35 and Nevada to $4.81, well above the national baseline.
The Economic Drag on Working-Class Household Budgets
In lower-cost regions across the South and Gulf Coast—including Texas at $3.64, Mississippi at $3.66, and Louisiana at $3.68—gasoline prices remain lower than the national average due to proximity to primary refineries and lower state fuel taxes.
However, even in these lower-tax states, prices are up significantly compared to last year. For working-class households that drive long daily distances in rural and suburban areas, spending an extra $50 to $80 per week on fuel directly reduces disposable income for medical bills, back-to-school clothing, and family savings.
Consumer surveys show that elevated gas prices act as a direct psychological drag on consumer confidence, prompting households to cut back on restaurant dining, weekend travel, and non-essential retail purchases.
Long-Term Outlook for American Energy Policy and Consumers
The current pre-election energy crisis highlights the deep structural challenges facing the American energy landscape as the nation balances fossil fuel reliance with the clean energy transition.
Evaluating the Limits of Strategic Petroleum Reserve Interventions
Faced with political backlash over high pump prices, policymakers frequently debate emergency interventions using the United States Strategic Petroleum Reserve. In prior energy emergencies, emergency crude releases provided temporary price relief by injecting millions of barrels of crude into commercial refining channels.
However, the utility of the Strategic Petroleum Reserve is significantly diminished today. Following historic emergency drawdowns over recent years, the reserve holds roughly 375 million barrels of crude—far below its historical peak storage capacity of more than 700 million barrels.
Energy analysts emphasize that releasing a limited volume of crude from emergency caverns cannot solve structural global refining bottlenecks or restore disabled foreign export pipelines. Furthermore, draining emergency reserves during an active international military conflict raises national security concerns, leaving policymakers with few administrative tools to bring pump prices down quickly.
The Permanent Economic Burden of Energy Volatility
The reality confronting American consumers is that fuel price volatility has become a permanent feature of the modern macroeconomic landscape. As global geopolitical fragmentation deepens and international maritime trade routes face persistent security threats, the era of predictable, cheap fossil fuels is receding.
Financial market indicators show high probabilities that retail gasoline prices will remain elevated above $4.25 to $4.60 per gallon through Election Day and into the winter.
This persistent price pressure is accelerating long-term consumer shifts toward energy efficiency. Commercial fleet operators are expanding investments in electric delivery vans and hybrid logistics trucks to eliminate diesel exposure, while retail car buyers are prioritizing hybrid powertrains and electric vehicles to insulate their household budgets from future oil price shocks.
A Defining Economic Test at the Ballot Box
The surge in United States gasoline prices to historic election-season highs marks a critical turning point for the national economy and the political landscape. What began as distant geopolitical friction in the Middle East has traveled across global energy markets directly into the gas tanks of millions of American workers.
With regular gasoline averaging over $4.30 per gallon, diesel setting all-time records above $6.00, and crude oil holding above $100 per barrel, the financial pressure on American families is real, immediate, and visible every single day.
As voters prepare to cast their ballots in critical midterm elections, the price displayed on the corner gas station sign will loom large in the minds of the electorate. The convergence of global energy bottlenecks, persistent inflation, and central bank interest rate dilemmas proves that no matter how advanced the modern economy becomes, the physical price of energy remains the ultimate engine of economic prosperity and political change.