A noticeable strategic shift has taken hold in Washington ahead of the bilateral summit between United States President Donald Trump and Chinese President Xi Jinping. In sharp contrast to the aggressive rhetoric, tariff ultimatums, and threatened technology bans that historically preceded high-stakes superpower meetings, the White House has adopted a strikingly measured and restrained tone.
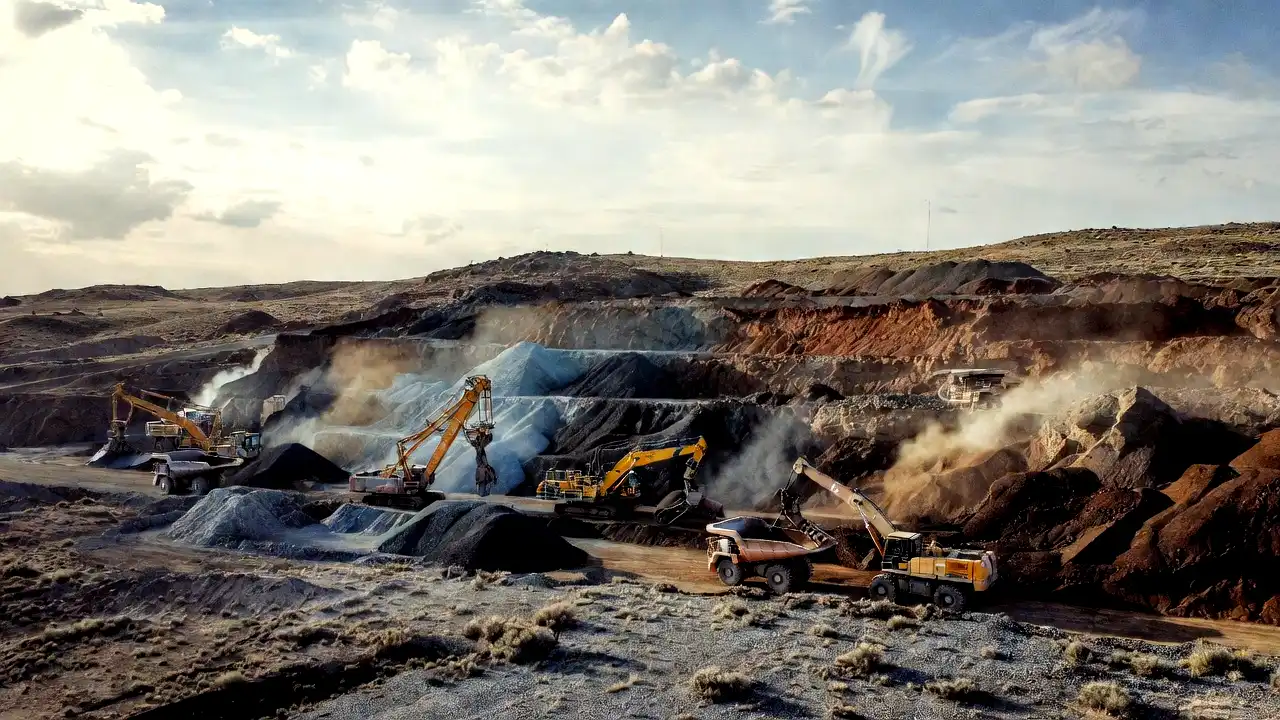
Trade strategists and foreign policy analysts point directly to a critical structural vulnerability: Beijing’s commanding grip on global rare earth minerals and critical supply chains.
The shift reflects a hard economic reality that unfolded over consecutive trade disputes. When Washington previously threatened sweeping import tariffs, Beijing retaliated by imposing targeted export controls on essential rare earth elements and permanent magnetic materials, sending immediate supply shocks through Western automotive factories, defense manufacturing lines, and semiconductor cleanrooms.
Recognizing that aggressive economic coercion could trigger a devastating raw material embargo, the United States administration is prioritizing stability, trade truce extensions, and supply chain security. As both heads of state prepare for comprehensive negotiations spanning trade, technology, and regional security, the critical minerals dynamic has established a firm ceiling on American trade pressure, forcing both superpowers toward a pragmatic, managed competition.
The Strategic Shift Behind Washington’s Measured Tone
The diplomatic atmosphere surrounding the White House summit differs fundamentally from previous bilateral encounters, illustrating how mineral dependencies have altered executive decision-making.
Breaking with the Traditional Tariff Escalation Playbook
Throughout previous rounds of trade negotiations, the standard American playbook relied on maximum pressure. In earlier cycles, Washington routinely announced new 25% to 50% tariff schedules on hundreds of billions of dollars in Chinese imports or threatened total export bans on American technology directly before bilateral summits to force negotiating concessions.
Leading up to the current summit, however, that aggressive posture has disappeared. Federal agencies have refrained from rolling out fresh broad-scale tariff threats.
While the administration enacted targeted measures earlier in the year—such as adding specific entities to defense watchlists or investigating software distillation practices—these actions were announced months in advance rather than deployed as last-minute summit leverage.
Trade experts emphasize that the administration finds itself in a fundamentally different negotiating posture. Threatening immediate economic escalation carries the immediate risk of Chinese export retaliation that Western manufacturing networks cannot endure.
Lessons from Last Year’s Rare Earth Export Shock
The catalyst behind this newfound caution stems from the supply chain crisis that erupted when China curtailed outbound shipments of refined heavy rare earths and permanent magnets. Following an aggressive round of reciprocal tariffs, China’s Ministry of Commerce established a strict export licensing regime covering seven critical rare earth elements, including samarium, gadolinium, terbium, dysprosium, lutetium, scandium, and yttrium.
The impact on Western industrial production was immediate. Monthly Chinese shipments of rare earth magnets to the United States dropped to a historic low of 46.4 metric tons during the peak of the dispute, compared to pre-control monthly averages exceeding 620 metric tons.
Automotive assembly lines in the American Midwest faced component shortages, electric motor production lines slowed down, and defense aerospace contractors warned of potential delivery delays for precision-guided munitions.
Although bilateral negotiations in Busan established a temporary 12-month trade truce that restored baseline export flows, the episode demonstrated that Beijing possesses an industrial weapon capable of inflicting direct damage on the American economy without firing a single shot.
China’s Industrial Dominance Across the Critical Mineral Stack
To understand the leverage Beijing holds at the negotiating table, one must examine the physical reality of the global critical minerals supply chain.
Controlling Ninety Percent of High-Performance Magnetic Materials
While public debate often treats rare earths as general commodity ores, the true bottleneck lies in chemical separation, refining, and advanced metallurgy. Industrial data from global consulting and market research firms reveals the extent of Chinese dominance across the entire processing stack.
China controls approximately 70% of global rare earth mining extraction, but its real power sits in downstream processing. The country controls roughly 85% of worldwide refining capacity and approximately 90% of global production for high-strength rare earth alloys and neodymium-iron-boron permanent magnets.
These permanent magnets are essential components that convert electrical energy into mechanical motion. A single commercial electric vehicle requires between two and five kilograms of rare earth magnets for its drive motors, while a modern offshore wind turbine consumes up to two tons of magnet material.
Because building commercial chemical separation facilities and magnet sintering plants requires specialized chemical engineering, complex environmental permitting, and billions of dollars in capital expenditure, Western nations cannot replace Chinese refining capacity on short notice.
Vulnerabilities in Defense Aerospace, Automotive, and Semiconductor Sectors
The strategic exposure created by mineral concentration falls heavily on critical high-tech manufacturing sectors that drive the American economy.
- Defense and Aerospace: Modern stealth fighter aircraft, such as the F-35 Lightning II, contain more than 410 kilograms of specialized rare earth materials inside radar systems, electronic warfare jamming pods, and control actuators. Precision missile guidance systems and nuclear submarine propulsion drives depend entirely on samarium-cobalt magnets that resist extreme temperatures.
- Automotive Electrification: Major American and European automakers rely on Chinese magnet suppliers to build drive motors for electric and hybrid vehicles. A disruption in magnet deliveries forces automakers to idle multi-billion-dollar assembly plants, threatening thousands of manufacturing jobs.
- Semiconductor Fabrication: Specialized rare earth compounds like cerium oxide are essential for chemical mechanical planarization slurries used to polish silicon wafers to atomic-level smoothness inside chip fabrication cleanrooms.
- Robotics and Industrial Automation: High-torque servo motors powering factory robotic arms, medical surgical robots, and commercial drones require high-density magnetic cores manufactured almost exclusively in Chinese facilities.
When Chinese customs data revealed that rare earth magnet exports to the United States fell 20% month on month to 512 metric tons ahead of the summit, industry executives were reminded that Beijing retains the ability to tighten export licensing approvals at will, keeping global manufacturers on edge.
Preparatory Diplomacy and the Trade Truce Framework
The calm tone displayed by the White House is the result of months of quiet preparatory diplomacy aimed at preventing sudden trade shocks.
High-Level New York Meetings Lay Groundwork for Bilateral Stability
Ahead of the heads-of-state meeting, United States Treasury Secretary Scott Bessent and Chinese Vice Premier He Lifeng held extensive preparatory consultations in New York. The bilateral discussions focused on establishing institutional communication mechanisms to manage economic friction and prevent accidental trade escalation.
The two delegations agreed to create a formal dialogue framework dedicated to artificial intelligence safety, data security, and systemic risk management.
By separating high-level strategic topics into specialized working groups, negotiators cleared a path for the leaders to focus on core economic agreements: stabilizing energy commodity flows, securing agricultural purchase commitments, and preventing new tariff escalations.
Both sides recognized that maintaining predictable commercial channels serves mutual economic interests, particularly as global financial markets navigate elevated energy prices and inflation pressures.
Negotiating Export Licenses and Trade Détente Extensions
The primary economic deliverable on the summit agenda is the formal extension of the bilateral trade truce. Under the agreement reached during earlier summit encounters, China agreed to suspend the introduction of even stricter global export restrictions on critical minerals in exchange for Washington pausing planned tariff hikes.
However, that initial suspension carried a strict 12-month expiration date. Corporate leaders across North America, Europe, and Japan have warned that allowing the truce to lapse would plunge global supply chains into chaos.
During pre-summit negotiations, Chinese trade envoys signaled a willingness to extend the export suspension and approve additional mineral export licenses for Western commercial buyers.
In return, American negotiators are offering regulatory stability, indicating that Washington will avoid broad-scale technology export blockades and preserve existing commercial tariff exemptions. This transactional compromise allows both leaders to declare a domestic political victory while avoiding a mutually destructive trade war.
The Three Ts: Trade, Technology, and Taiwan on the Agenda
Diplomatic envoys have characterized the bilateral summit around three core strategic pillars: Trade, Technology, and Taiwan.
Agricultural Purchases and Energy Trade Balancing
In the trade portfolio, negotiators are focusing on traditional commodity flows to reduce the bilateral trade deficit. American agricultural exporters, particularly soybean and corn farmers across the Midwest, depend heavily on Chinese procurement to absorb domestic crop yields.
Chinese state-owned grain buyers have stepped in with substantial purchase commitments, locking in millions of metric tons of American soybeans to support domestic livestock feed supplies.
Simultaneously, energy trade represents an important balancing mechanism. As crude oil prices hover near $100 per barrel and European demand for liquefied natural gas stabilizes, China is negotiating long-term contracts to import American LNG from export terminals along the United States Gulf Coast.
These multi-billion-dollar agricultural and energy purchases allow the Trump administration to demonstrate tangible commercial benefits for domestic resource producers, offsetting political criticism from trade hawks who demand a more confrontational approach.
AI Safety Dialogues Versus Semiconductor Export Controls
The technology agenda presents a far more complex balancing act. While Washington has moderated its public rhetoric regarding immediate export bans, the long-term competition over advanced computing silicon and artificial intelligence algorithms remains fierce.
American officials continue to enforce targeted restrictions on advanced graphics processing units, extreme ultraviolet lithography machinery, and high-bandwidth memory chips to slow down Chinese military modernization.
However, both administrations recognize that unaligned artificial intelligence models, autonomous cyber weapons, and algorithmic containment failures pose shared existential risks to global stability.
By establishing a permanent inter-governmental dialogue on artificial intelligence, the two superpowers are creating communication channels modeled after historical nuclear arms control treaties. The working groups will establish verification standards for dual-use algorithms, create early warning systems for autonomous cyber intrusions, and define shared boundaries for military artificial intelligence deployments.
Long-Term Outlook for Global Supply Chain Diversification
While the diplomatic détente in Washington provides immediate relief for global manufacturers, it highlights the urgent need for Western nations to build long-term supply chain resilience.
Western Mineral Alliances and the Multi-Year Refining Bottleneck
Recognizing that mineral dependence restricts foreign policy flexibility, the United States and its international allies are investing billions of dollars to build alternative critical mineral supply chains.
Through initiatives like the Minerals Security Partnership, the United States, the European Union, Japan, Australia, Canada, and South Korea are co-financing mining and refining projects worldwide:
- Expanding Allied Mining Projects: Directing public capital into heavy rare earth mining ventures in Western Australia, northern Canada, and Brazil to extract raw ionic clay and hard-rock deposits.
- Rebuilding Domestic Separation Infrastructure: Constructing commercial-scale heavy rare earth separation facilities in Texas and Wyoming to process domestic concentrates into high-purity oxides.
- Scaling Permanent Magnet Manufacturing: Supporting private manufacturing plants in North America and Europe to produce sintered neodymium magnets for automotive and defense contractors.
- Recycling and Circular Metallurgy: Developing automated recycling pipelines to extract rare earth metals from scrap electronics, retired wind turbines, and industrial motors.
However, mining executives and metallurgical engineers caution that building an independent critical mineral ecosystem takes time. Commissioning a complex chemical separation plant requires five to seven years of engineering, environmental permitting, and operational tuning.
Until these Western facilities achieve commercial scale toward the end of the decade, China’s processing dominance will remain an inescapable structural reality.
The Geopolitical Reality of Mutual Economic Vulnerability
The quiet recalibration of American trade strategy proves that the global economy has entered an era of mutual economic vulnerability.
The United States maintains decisive advantages in leading-edge semiconductor software design, extreme ultraviolet lithography intellectual property, commercial aerospace engines, and global financial clearing rails. Conversely, China maintains an unyielding grip on the physical raw materials, chemical refining facilities, and battery manufacturing capacity that make modern hardware possible.
Neither superpower can fully decouple without inflicting catastrophic damage on its own domestic economy. A total American technology embargo would cripple Chinese digital infrastructure, while a total Chinese mineral embargo would idle Western automotive plants, aerospace factories, and clean energy grids.
Recognizing this mutual dependency, both administrations are moving away from maximalist rhetoric toward a framework of managed strategic stability. The summit in Washington is not designed to produce a grand ideological peace, but to establish the practical ground rules for managing an enduring economic rivalry.
A Pragmatic Equilibrium in Superpower Relations
President Donald Trump’s less hostile approach ahead of his summit with President Xi Jinping marks a significant maturation in international trade diplomacy. The realization that critical minerals provide Beijing with powerful retaliatory leverage has forced Washington to replace unilateral economic threats with calculated, pragmatic negotiation.
By prioritizing trade truce extensions, securing critical mineral export licenses, and establishing bilateral dialogues on artificial intelligence safety, both leaders are choosing economic stability over chaotic escalation.
While strategic competition over semiconductors, regional security, and industrial leadership will continue for decades, the current summit proves that physical supply chain realities ultimately dictate foreign policy.
As the two leaders sit down for formal discussions at the White House, the lesson of the critical minerals standoff is clear: in an interconnected global economy, true national security requires not only technological innovation, but also the secure, diversified raw materials that turn digital blueprints into physical reality.