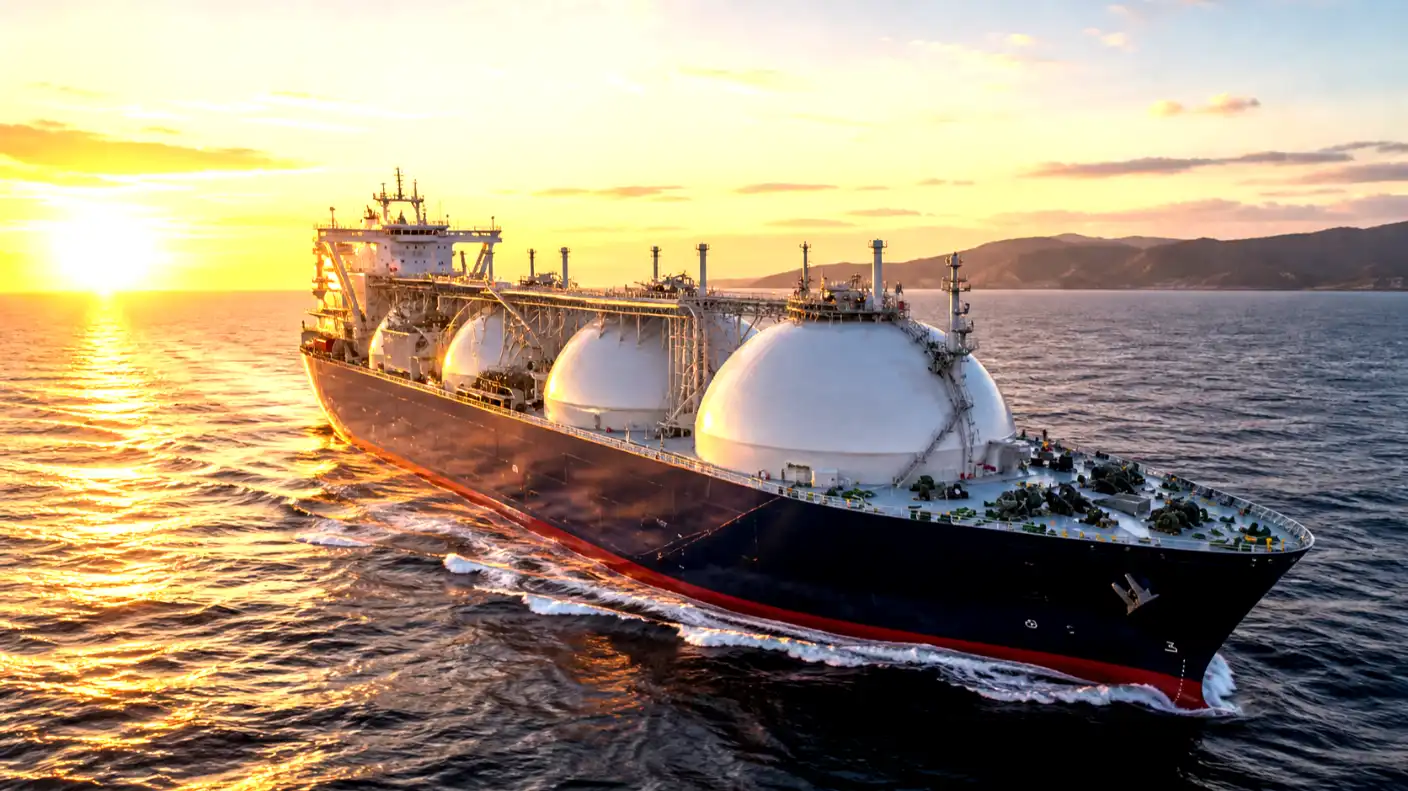
For over a decade, international energy majors and multilateral development institutions marketed Liquefied Natural Gas as the indispensable bridge fuel for emerging Asia. The narrative was straightforward: fast-growing developing nations from South Asia to the South China Sea would replace aging, polluting coal-fired power plants with cleaner, flexible gas turbines fueled by a steady stream of imported chilled methane.
That bridge fuel promise has collapsed under the weight of catastrophic economics. Facing a staggering collective gas import bill exceeding $7 billion, crippling foreign currency deficits, and repeated currency devaluations, developing Asian nations are systematically souring on LNG. Countries like Pakistan, Bangladesh, Vietnam, and the Philippines have discovered that relying on volatile global spot markets leaves their power grids vulnerable to international energy shocks, fiscal insolvency, and widespread industrial blackouts.
Rather than doubling down on multi-billion-dollar import infrastructure, governments across emerging Asia are executing a sharp strategic retreat. They are canceling planned gas-fired power stations, pausing floating storage terminal projects, returning to domestic coal reserves, and accelerating solar and wind deployments to protect their national sovereignty and economic survival.
The Crippling Economics of Imported Liquefied Natural Gas
The disillusionment with imported natural gas across developing Asian economies is rooted in an unyielding financial reality: low-income, price-sensitive electricity markets cannot absorb high-cost, dollar-denominated fuel imports.
Foreign Exchange Depletion and Dollar Shortages in South Asia
The macroeconomic shock of imported LNG hit South Asia with extreme severity. In nations where retail electricity tariffs are politically sensitive and heavily subsidized, state utilities must pay for imported fuel cargoes in United States dollars while collecting revenue from domestic consumers in depreciating local currencies.
When global energy prices skyrocketed following international geopolitical disruptions, countries like Pakistan and Bangladesh burned through billions of dollars in foreign exchange reserves just to keep baseline electrical grids running. In Pakistan, the national petroleum and gas import bill surged past $17.5 billion in a single fiscal year, with LNG purchases consuming a massive share of dwindling central bank dollar reserves.
The resulting currency drain depleted foreign reserves to levels that barely covered a few weeks of total national imports, pushing the country to the brink of sovereign debt default and forcing emergency balance-of-payments bailouts from the International Monetary Fund.
State energy buyers found themselves unable to open letters of credit with commercial banks to pay for contracted LNG cargoes. As international commodity trading houses diverted shipments to wealthier European buyers who could pay higher cash premiums, South Asian cities were plunged into 12-to-18-hour daily rolling blackouts, crippling export-oriented textile mills and triggering widespread economic contraction.
Volatile Spot Markets and European Competition for Cargoes
The vulnerability of developing Asian economies was magnified by the structure of the international gas trade. While mature East Asian economies like Japan, South Korea, and Taiwan purchase the vast majority of their LNG through rigid, multi-decade contracts indexed to crude oil prices, developing Asian buyers relied heavily on the short-term spot market to meet fluctuating power demand.
When European nations lost Russian pipeline gas supplies, European utilities swept into global markets with virtually unlimited financial firepower, bidding spot LNG prices above $30 to $50 per million British thermal units. Developing Asian nations could not compete against European sovereign balance sheets.
International commodity suppliers routinely exercised contractual cancellation clauses, paying small break fees to Asian state buyers to re-route contracted tankers to European terminals for massive windfall profits.
This experience proved to policymakers in Islamabad, Dhaka, and Manila that the global LNG market is fundamentally unreliable during international supply crunches. When supplies tighten, poorer nations are systematically priced out of the market, leaving their domestic industries starved of electricity.
Regional Casework: How Key Emerging Markets Are Pivoting
The fallout from volatile gas prices has reshaped national energy roadmaps across South and Southeast Asia, turning ambitious gas expansion plans into cautionary tales.
Pakistan Abandons New Gas Plants for Thar Coal and Renewables
Pakistan has executed the most dramatic policy reversal in the region. A decade ago, the government constructed several large-scale combined-cycle gas turbine power stations, intending to build an energy system powered primarily by imported LNG.
Following consecutive years of fuel shortages, unpaid import bills, and currency crises, the Pakistani government officially froze all plans to construct new power plants that run on imported fossil fuels. Instead, the energy ministry enacted a policy to convert existing imported-coal and gas infrastructure to run on domestic lignite coal extracted from the Thar Desert.
Furthermore, the government launched massive competitive auctions for utility-scale solar farms and decentralized rooftop photovoltaic systems. By substituting imported dollar-denominated gas with domestic resources, Pakistan aims to eliminate more than $2 billion in annual foreign exchange outflows, insulating its national budget from international commodity traders.
Bangladesh Confronts Import Arrears and Grid Blackouts
In Bangladesh, the rapid exhaustion of domestic gas fields in the Bengal Basin prompted state planners to construct floating storage and regasification units off the coast of Cox’s Bazar, projecting that imported LNG would supply over 40% of the nation’s total power generation by 2030.
However, the reality of high import costs shattered those projections. The state-owned energy agency Petrobangla accumulated hundreds of millions of dollars in overdue payment arrears to international suppliers and trading houses. To conserve foreign currency, the government was forced to shut down fertilizer plants, ration gas to commercial manufacturing zones, and idle modern gas-fired power stations totaling thousands of megawatts in capacity.
The resulting power shortages severely impacted the ready-made garment sector, which generates over 80% of Bangladesh’s export earnings. In response, Bangladeshi authorities have paused several proposed onshore LNG regasification terminals, renegotiated existing long-term supply pacts, and increased cross-border electricity imports from neighboring regional grids while expanding solar power targets across rural districts.
Vietnam and the Philippines Stalled by Financing and Pricing Impasses
In Southeast Asia, Vietnam and the Philippines were heralded by global energy corporations as the next major growth frontiers for LNG infrastructure. Both nations formulated national energy master plans outlining dozens of gigawatts of new gas-fired power capacity to replace retiring coal plants and offset depleting offshore domestic gas fields like Malampaya.
Yet, commercial execution has ground to a near-total standstill. In Vietnam, the implementation of the National Power Development Plan 8 has stalled because international project developers and state utility Vietnam Electricity cannot agree on long-term Power Purchase Agreements.
Foreign investors demand government-backed sovereign guarantees that the state utility will buy minimum volumes of high-priced gas electricity for 20 years, while Vietnamese regulators refuse to pass volatile international fuel price risks directly onto domestic consumers and manufacturing export hubs.
In the Philippines, commercial gas power developers face similar grid-tariff impasses, prompting conglomerates to extend the operational life of domestic offshore fields and pivot capital toward massive utility-scale solar-plus-storage installations.
The Structural Shift Back to Coal and Acceleration of Renewables
The retreat from imported LNG has produced a profound structural realignment in how emerging markets evaluate energy security versus environmental decarbonization.
Domestic Energy Security Trumps Clean Energy Bridge Rhetoric
For developing nations, the primary mandate of national energy policy is affordability and uninterrupted availability. Energy poverty directly suppresses economic development, job creation, and political stability.
When forced to choose between intermittent, expensive imported gas and affordable, locally available solid fuels, governments have consistently chosen energy security. Across Asia, utilities are extending the operational lifespans of young, highly efficient supercritical coal-fired power stations.
India, while expanding its renewable energy capacity at a world-leading pace, has explicitly prioritized domestic coal mining and coal-fired baseload generation, rejecting large-scale imported LNG adoption for base power generation due to prohibitive costs. In the eyes of emerging market finance ministers, burning domestic coal or buying regional pipeline power carrying predictable local-currency costs is far safer than gambling national solvency on international LNG spot pricing.
Utility-Scale Solar and Wind Squeeze Out Gas-Fired Peakers
While coal provides baseline power, the economic space previously reserved for flexible gas-fired peaking plants is being rapidly captured by renewable energy and battery storage systems.
The levelized cost of electricity for utility-scale solar photovoltaics has plunged by more than 85% over the past decade, with newly contracted solar projects across Asia delivering power at rates between $0.03 and $0.05 per kilowatt-hour. In contrast, power generated from imported LNG operating at $12 to $15 per MMBtu costs between $0.09 and $0.14 per kilowatt-hour before factoring in domestic transmission charges.
As utility-scale lithium iron phosphate battery energy storage systems fall below $100 per kilowatt-hour at the pack level, pairing solar and wind farms with four-to-eight-hour battery storage has become significantly cheaper than constructing and fueling open-cycle gas peakers. Renewable energy delivers zero-fuel-cost electricity that requires zero foreign currency expenditure, making clean energy the ultimate economic hedge against international commodity inflation.
Global LNG Supply Glut Faces a Demand Vacuum in Asia
The strategic retreat across developing Asia carries massive financial consequences for the global natural gas industry, which has committed hundreds of billions of dollars to expanding export infrastructure based on flawed demand forecasts.
Qatar and US Export Expansions Risk Stranded Assets
Energy majors in the United States, Qatar, Australia, and East Africa are currently constructing the largest wave of new LNG liquefaction export terminals in history. Qatar is pouring tens of billions of dollars into its North Field East and North Field South expansion projects to raise national export capacity by over 60%, reaching 142 million tons per annum.
Simultaneously, dozens of export terminals along the United States Gulf Coast are adding tens of millions of tons of new liquefaction capacity. These multi-billion-dollar investments were approved under the assumption that developing Asian nations would absorb vast volumes of surplus gas throughout the late 2020s and 2030s.
With emerging Asian buyers canceling import projects and demand growth stalling across traditional buyers like Japan and Europe, the global LNG market is heading toward a massive structural supply glut. Energy analysts warn that without price-elastic demand from emerging Asia, global liquefaction utilization rates will fall, depressing international gas prices and threatening billions of dollars in export infrastructure with asset write-downs and stranded capital.
Contract Flexibility Demands and Shorter Tenor Negotiations
The changing market dynamics have shifted bargaining power away from global LNG sellers toward the few buyers remaining in the market. The rigid, seller-friendly contracts of the past are no longer viable in developing Asia.
Emerging market buyers are refusing to sign traditional 20-year, oil-indexed take-or-pay contracts that include restrictive destination clauses preventing the resale of unused fuel. Instead, buyers are demanding flexible, short-tenor agreements spanning three to five years, full destination flexibility, and hybrid pricing formulas that incorporate Henry Hub and regional power-market indices.
Furthermore, buyers are insisting on lower contract slopes—the percentage ratio linking gas prices to Brent crude—demanding slopes below 11% to 12% to protect domestic utilities from oil price spikes. Suppliers that refuse to offer flexible, low-cost commercial terms are finding themselves completely shut out of Asian procurement tenders.
Long-Term Outlook for Asian Energy Systems and Decarbonization
The sourcing of developing Asian nations on imported LNG marks a fundamental turning point in the global energy transition, establishing a new reality for international climate policy and infrastructure development.
Re-Evaluating the Bridge Fuel Narrative in the Global South
The collapse of the LNG bridge fuel narrative exposes the deep flaws in Western-designed energy transition roadmaps that assumed developing nations could replicate the fuel-switching models of wealthy advanced economies.
In Europe and North America, well-capitalized power markets and deep domestic pipeline networks allowed gas to displace coal smoothly while renewable infrastructure matured. In emerging Asia, however, imported LNG proved to be not a bridge, but an expensive, volatile trap that drained national treasuries, inflated consumer electricity bills, and destabilized electrical grids.
International climate finance institutions and multilateral development banks are shifting their funding strategies, abandoning subsidies for midstream fossil gas infrastructure in favor of financing high-voltage cross-border power grids, pumped-storage hydropower projects, and localized renewable manufacturing hubs across the Global South.
Building Resilient Domestic Grids in an Era of Commodity Shocks
The overarching lesson learned by developing Asian nations over the past five years is that true national security requires energy independence. An economy whose factories and households depend on ships carrying foreign chilled gas across contested oceans is permanently exposed to external geopolitical extortion and commodity price volatility.
Over the coming decades, the Asian energy landscape will be defined by regional integration, domestic resource maximization, and aggressive electrification:
- Regional Power Interconnectors: Expanding cross-border high-voltage direct current transmission lines under initiatives like the ASEAN Power Grid, allowing nations to share surplus hydroelectric power from Laos and Bhutan across regional borders.
- Decentralized Renewable Networks: Mass deployment of distributed rooftop solar arrays and agricultural microgrids that bypass fragile centralized distribution networks and eliminate fuel transport costs.
- Long-Duration Energy Storage: Investing in regional pumped-storage hydroelectric stations and domestic battery fabrication plants to provide clean, dispatchable grid balancing.
- Maximizing Domestic Offshore Resources: Prioritizing the development of sovereign domestic offshore gas reserves strictly for specialized industrial manufacturing and petrochemical synthesis rather than inefficient power generation.
A Decisive Realignment in Global Energy Power
Developing Asia’s retreat from Liquefied Natural Gas marks the end of an era of uncritical fossil fuel expansion. The painful experience of managing $7 billion gas import bills, depleted foreign exchange reserves, and prolonged electrical blackouts has taught emerging economies that imported gas is an unaffordable luxury they cannot sustain.
By rejecting volatile spot-market imports and reallocating capital into domestic renewables, grid modernization, and regional energy sharing, developing Asian nations are taking control of their economic destinies. The global energy transition in the Global South will not be paved with imported fossil fuels, but built upon the solid foundation of domestic clean energy, financial resilience, and national self-reliance.